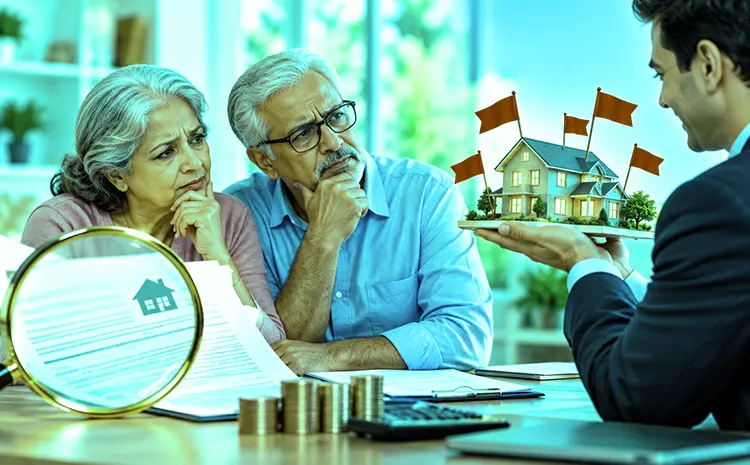

A jumbo reverse mortgage can look like a lifeline when home values are high and retirement budgets feel painfully tight. The glossy brochure arrives. The lender sounds warm. The numbers seem almost magical. No monthly mortgage payments, access to equity, and the promise of more breathing room. For many older homeowners, that can stir a mix of hope and relief.
But this is also where emotions can cloud judgment.
When an offer is not right for you, the warning signs are often subtle at first. They hide behind polished language, upbeat sales pitches, and a rush to “act now.” If you are considering a loan against a high-value home, you deserve clarity, not pressure. You deserve patience, not confusion. And you deserve to know how to spot the difference between a useful financial tool and a costly mistake.
Understanding the Basics of a jumbo reverse mortgage
A jumbo reverse mortgage is generally designed for homeowners with properties that exceed the lending limits of standard reverse mortgage programs. Because the home value is higher, the loan may allow access to a larger amount of equity.
That sounds appealing. It can be appealing.
Still, bigger does not always mean better.
These loans are not one-size-fits-all. Terms vary by lender. Fees can be different. Interest structures can be more complex than you expect. Some offers are fair and thoughtfully designed. Others are simply dressed up to look that way.
A neighbor once described her meeting with a lender as “exuberant from the moment he walked in.” He praised her home, praised the market, praised the “fantastic opportunity” in front of her. His energy was infectious. For a moment, she felt exuberant too. Then, later that evening, she realized she could not clearly explain the costs he had described. That is the moment to pause. Excitement is not understanding.
Watch for Pressure Disguised as Help
One of the clearest signs of an unsuitable offer is pressure.
A trustworthy lender or advisor should give you room to think, compare, ask questions, and involve family members or trusted professionals if you choose. If someone keeps pushing you to sign quickly, that is not efficiency. That is a warning sign.
Pressure can show up in different ways:
- “This offer may not be available next week.”
- “You do not need to overthink this.”
- “Most people your age just want the cash flow.”
- “We can handle the details later.”
That kind of language can feel comforting in the moment, especially if you are tired, worried, or overwhelmed. But major financial decisions should never be rushed. If an offer depends on urgency more than transparency, your reservation is justified.
A short story comes to mind. A retired couple once sat through a loan presentation and smiled politely through the whole thing. Everything sounded polished. Everything sounded easy. Yet as they walked the lender to the door, the wife quietly said she had a “reservation she could not shake.” That small inner pause turned out to matter. After reviewing the paperwork with an independent counselor, they found unexpected fees buried in the terms. Sometimes your unease notices a problem before your mind can name it.
Compare reverse mortgage jumbo loans With a Critical Eye
Not all reverse mortgage jumbo loans are structured the same way. That is why comparison matters so much.
An unsuitable offer often becomes obvious when you place it beside another one.
Look closely at:
- Interest rates and whether they are fixed or variable
- Origination fees and closing costs
- Servicing fees, if any
- Rules about property upkeep, taxes, and insurance
- Payment options and access to funds
- Conditions that could trigger problems later
Some offers look generous upfront but become expensive over time. Others seem flexible, but the repayment conditions or lender obligations may put you in a vulnerable position later.
Ask for every figure in writing. Ask what happens if home values change. Ask how the balance grows over time. Ask what your heirs may need to know. A suitable lender will welcome those questions. An unsuitable one may grow noticeably less patient.
The Fine Print Tells the Emotional Truth
There is something deeply unsettling about realizing that the warm conversation you had does not match the paperwork in front of you.
That disconnect matters.
If the lender’s verbal explanation sounds simple but the written terms feel confusing, technical, or incomplete, slow down. Confusion is expensive. Financial products tied to your home should not leave you guessing about costs, obligations, or long-term impact.
When comparing financing options, understanding jumbo reverse mortgage-rates and their associated costs is essential. This is especially important with reverse mortgage jumbo loans because the sums involved are often larger. A small misunderstanding about interest rates, fees, or repayment terms can turn into a serious financial setback, making careful research and comparison crucial before committing to a loan.
Read every document. Then read it again with someone you trust.
A family friend once shared a piece of advice that stayed with everyone around the table. He said, “If a financial offer makes you feel small for asking questions, walk away.” That advice came after he watched his sister sign a deal she barely understood because she did not want to seem difficult. You never need to trade dignity for access to your own equity.
Red Flags That Deserve Immediate Attention
Some warning signs are too important to ignore.
Be especially careful if:
- The lender avoids giving straight answers
- Fees are vague or seem unusually high
- You are encouraged to borrow more than you need
- The lender dismisses counseling or outside review
- The benefits are exaggerated while the risks are minimized
- You are told your family does not need to be involved
- The paperwork changes late in the process
A suitable offer should feel clear, respectful, and consistent. If it feels slippery, that is a problem.
It is also wise to think about your real goal. Are you trying to cover healthcare costs, pay off debt, stay in your home, or create more monthly stability? The right solution depends on the actual need. Sometimes a jumbo reverse mortgage may help. Other times, another financial path may be safer and less costly.
How to Protect Yourself Before You Sign
The strongest protection is slowing the process down.
Take these steps before agreeing to anything:
- Get independent counseling or professional review.
- Compare multiple lenders, not just one.
- Ask for a total cost breakdown over time.
- Discuss the decision with trusted family or advisors.
- Make sure you understand your ongoing responsibilities as a homeowner.
- Refuse to sign anything you do not fully understand.
You are not being difficult. You are being wise.
That matters because your home is not just an asset on paper. It is memory, safety, stability, and the place where your life happened. Any loan tied to it deserves your full attention.
The best mortgage offer is not the one wrapped in the brightest promises. It is the one that remains honest after the excitement fades, the sales pitch ends, and the documents are spread across the table. When you know what to watch for, you can protect your peace, your finances, and your future with far more confidence.